Australia’s online property advertising market is entering a new phase after REA Group moved to drop an exclusive listing requirement that has historically limited how agents and vendors could distribute listings across portals. The change appears set to lower switching costs, widen multi-portal strategies, and intensify competition on pricing, product quality, and data—while also creating new operational choices for agencies that have long optimised their workflows around a dominant platform.

U.S. existing-home sales have fallen to their lowest level in 14 months, a fresh signal that the long-stretched housing market is losing momentum. While demand is being constrained by affordability pressures and still-elevated mortgage rates, supply is finally rebuilding in many regions. The combination is shifting bargaining power, changing pricing dynamics, and reshaping expectations for buyers, sellers, and policymakers.
Seoul’s housing market has accelerated sharply, with reported price gains nearing 30% over the past two years in key districts, as an AI-led investment cycle reshapes where high-income jobs cluster and where capital flows. The result is a widening gap between wages and home values, heavier competition for limited supply in central neighborhoods, and a growing sense that even middle-class households are being priced out of the city’s most connected areas.
Australia’s housing market is undergoing its sharpest downturn since the late-1980s era of high interest rates and recession fears, with several analysts warning national home values could drop by 10–15% from recent peaks. The correction is being driven by rapidly higher borrowing costs, stretched affordability, and a reset in buyer sentiment after years of outsized gains. While the downturn is broad-based, the pace and depth vary by city, property type, and household exposure to variable-rate mortgages.
Australia’s housing market is losing momentum in a way that feels broader and more persistent than earlier soft patches: price declines are spreading across suburbs, clearance rates are cooling, and sellers are adjusting expectations. While conditions still vary sharply by city and property type, the common thread is a shift in bargaining power—away from vendors and toward buyers—driven by higher borrowing costs, stretched affordability, and a growing preference for waiting rather than overpaying.
Australia’s housing downturn is gathering momentum, with national home values falling for a fifth consecutive month and sentiment cooling across major cities. What began as a rate-driven slowdown is increasingly shaped by tighter borrowing capacity, affordability constraints, and shifting buyer expectations—factors that are now reshaping auction dynamics, listing strategies, and the outlook for both households and policymakers.
China is tightening housing rules again, aiming to contain financial risks that have accumulated in the property sector while steering the market toward a more sustainable footing. The shift reflects Beijing’s effort to balance multiple goals at once: preventing a renewed debt-driven real-estate boom, protecting households and banks from sharp price swings, and keeping construction and local-government finances from deteriorating further.
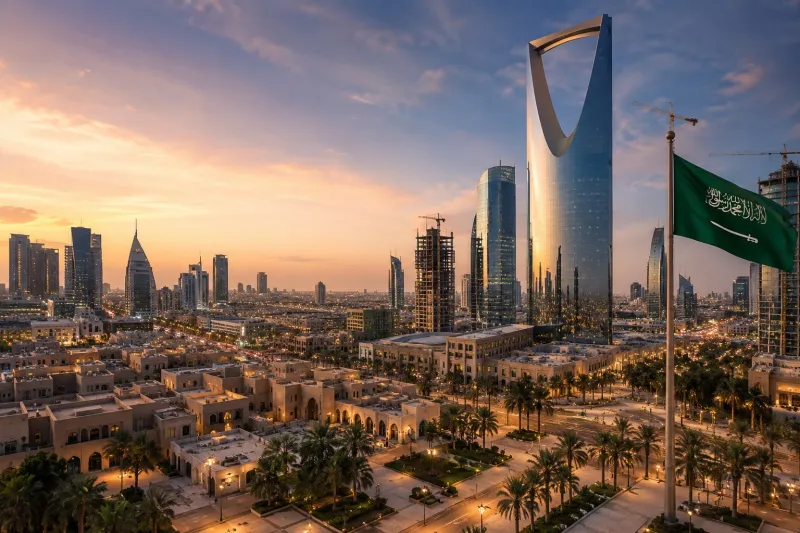
Saudi Arabia’s property market is showing continued resilience even as transaction momentum slows, according to CBRE. While fewer sales can signal a cooling cycle, the underlying picture remains supported by structural demand, government-backed development, and selective strength across residential, hospitality, and logistics. The shift is increasingly about composition—where demand concentrates, which price points move, and how developers and investors adapt—rather than a broad-based downturn.
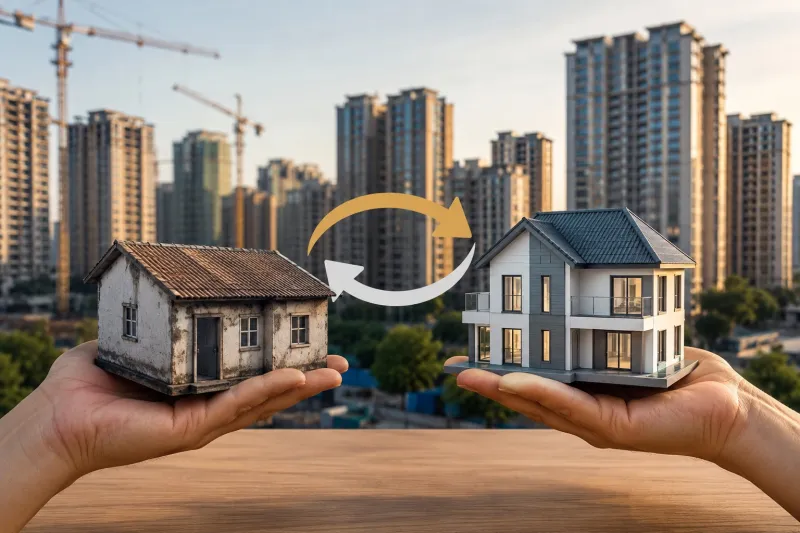
Binzhou, a city in China’s Shandong province, has rolled out a housing trade-in scheme designed to lower the friction of moving and rekindle demand in a sluggish property market. By encouraging households to swap older homes for newly built units—often with institutional support to handle the resale process—the policy aims to unlock pent-up upgrading demand, reduce inventories, and restore confidence without relying solely on broad, nationwide stimulus.