Australia’s online property advertising market is entering a new phase after REA Group moved to drop an exclusive listing requirement that has historically limited how agents and vendors could distribute listings across portals. The change appears set to lower switching costs, widen multi-portal strategies, and intensify competition on pricing, product quality, and data—while also creating new operational choices for agencies that have long optimised their workflows around a dominant platform.
Australia’s housing market is undergoing its sharpest downturn since the late-1980s era of high interest rates and recession fears, with several analysts warning national home values could drop by 10–15% from recent peaks. The correction is being driven by rapidly higher borrowing costs, stretched affordability, and a reset in buyer sentiment after years of outsized gains. While the downturn is broad-based, the pace and depth vary by city, property type, and household exposure to variable-rate mortgages.
Australia’s housing market is losing momentum in a way that feels broader and more persistent than earlier soft patches: price declines are spreading across suburbs, clearance rates are cooling, and sellers are adjusting expectations. While conditions still vary sharply by city and property type, the common thread is a shift in bargaining power—away from vendors and toward buyers—driven by higher borrowing costs, stretched affordability, and a growing preference for waiting rather than overpaying.
Australia’s housing downturn is gathering momentum, with national home values falling for a fifth consecutive month and sentiment cooling across major cities. What began as a rate-driven slowdown is increasingly shaped by tighter borrowing capacity, affordability constraints, and shifting buyer expectations—factors that are now reshaping auction dynamics, listing strategies, and the outlook for both households and policymakers.
Australia’s housing market is showing signs of cooling, with national home prices falling by around 2% and mortgage applications declining by more than 20%. The slowdown reflects weaker buyer activity and growing pressure on household finances, but analysts say the latest conditions do not yet point to a major housing crash.
The decline comes as higher borrowing costs continue to influence purchasing decisions. Elevated mortgage rates have made home loans more expensive, prompting some prospective buyers to delay purchases or reduce their budgets.
After years of relentless momentum, Australia’s housing market is losing speed. Falling or flat prices in key regions, longer selling times, and softer auction results are reshaping household expectations—and raising questions about what a property downturn means for consumption, construction, and financial stability. With interest rates higher than the ultra-low era and cost-of-living pressures still elevated, housing is increasingly acting less like an engine of growth and more like a potential drag on the broader economy.
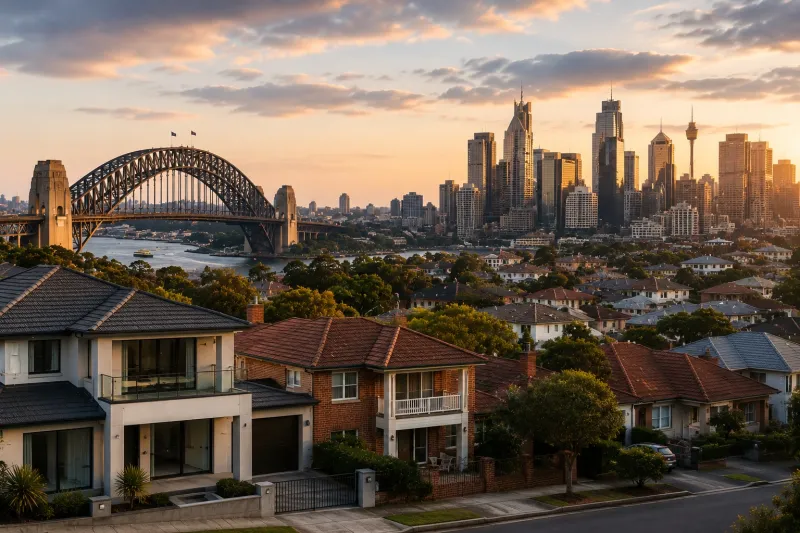
After years of outsized gains and rapid swings in borrowing conditions, Australia’s housing market is shifting into a cooler phase. The most visible changes are emerging in Sydney and Melbourne, where prices are correcting faster than in many other capitals as buyers become more rate-sensitive, listings rebuild, and vendors adjust expectations. While the downturn is not uniform, the balance of power is gradually moving away from sellers in several key segments.
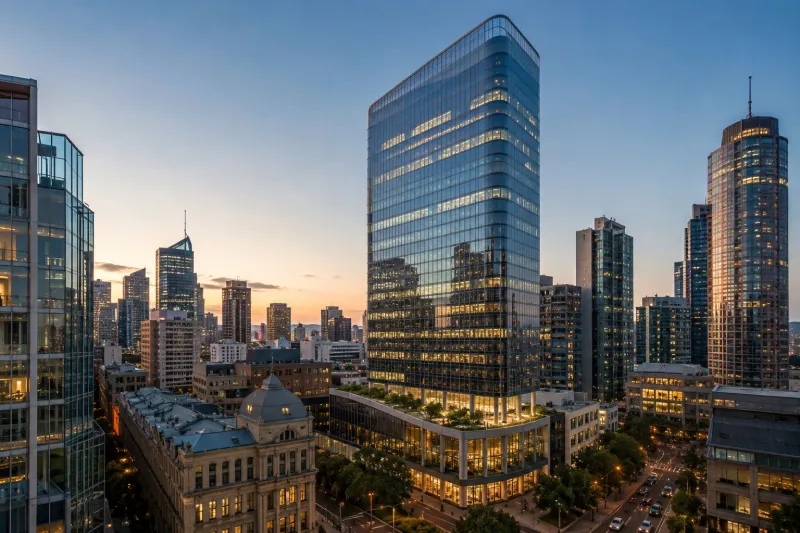
Australian real estate group Dexus has completed the sale of Brisbane's landmark 480 Queen Street office tower to global investment manager Barings in the city's largest-ever office property transaction. The record-breaking deal underscores the resilience of Australia's premium commercial real estate sector and reflects continued institutional demand for high-quality office assets despite ongoing challenges in the broader market.
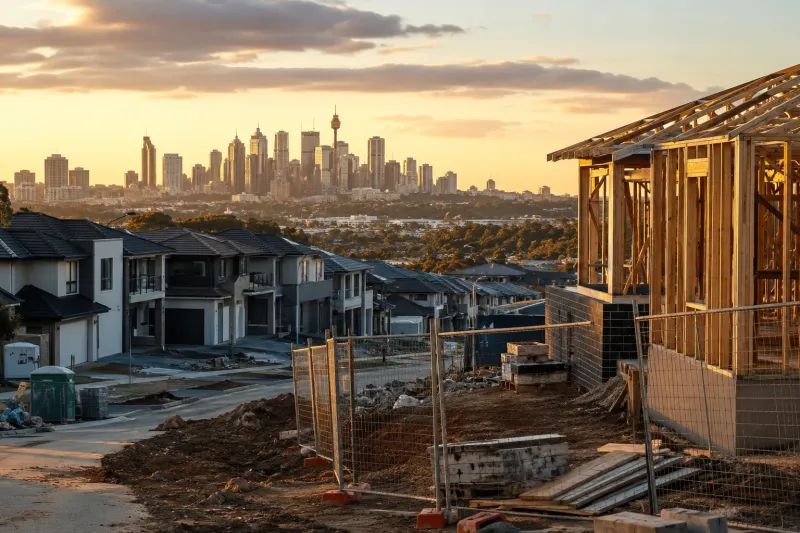
Australia’s housing shortage is intensifying as new home construction continues to lag behind population growth and policy ambitions. Despite national targets designed to accelerate supply, the pace of approvals, commencements, and completions is being constrained by high financing costs, trade shortages, planning delays, and fragile builder balance sheets. The result is a tightening market where rents rise faster, first-home buyers face steeper hurdles, and governments are forced to balance immediate relief with the long lead times of building.