After several years of sharp gains, Taiwan’s housing market is widely expected to move into a calmer phase by Q4 2026, with price growth cooling and transactions normalizing. A mix of tighter credit conditions, policy efforts to curb speculation, and shifting buyer preferences toward livability and value is reshaping demand—especially in the most overheated pockets. Stabilization does not necessarily imply falling prices across the board, but rather a market where affordability, financing and supply dynamics matter more than momentum.
China’s property slump is deepening as official data and market indicators point to a third consecutive month of falling home prices, reinforcing worries about weak demand, strained developer balance sheets, and the broader drag on consumption and local-government finances. Despite incremental policy easing, buyers remain cautious, inventories are elevated in many cities, and confidence has yet to reset—raising the stakes for Beijing’s next steps to stabilise a sector that has long been central to growth.
Seoul’s housing market has accelerated sharply, with reported price gains nearing 30% over the past two years in key districts, as an AI-led investment cycle reshapes where high-income jobs cluster and where capital flows. The result is a widening gap between wages and home values, heavier competition for limited supply in central neighborhoods, and a growing sense that even middle-class households are being priced out of the city’s most connected areas.
China is tightening housing rules again, aiming to contain financial risks that have accumulated in the property sector while steering the market toward a more sustainable footing. The shift reflects Beijing’s effort to balance multiple goals at once: preventing a renewed debt-driven real-estate boom, protecting households and banks from sharp price swings, and keeping construction and local-government finances from deteriorating further.
Binzhou, a city in China’s Shandong province, has rolled out a housing trade-in scheme designed to lower the friction of moving and rekindle demand in a sluggish property market. By encouraging households to swap older homes for newly built units—often with institutional support to handle the resale process—the policy aims to unlock pent-up upgrading demand, reduce inventories, and restore confidence without relying solely on broad, nationwide stimulus.
After several cautious years, foreign investors are returning to Japan’s real estate market in force, drawn by a rare mix of stability, scale, and pricing that still looks compelling next to many Western cities. A weaker yen has made acquisitions cheaper in foreign-currency terms, while Tokyo and other major hubs continue to offer deep liquidity, institutional-grade assets, and resilient tenant demand. From offices and logistics to hotels and multifamily housing, Japan is increasingly positioned as a core destination in global portfolios rather than a niche allocation.
China’s property sector continues to face significant challenges as the fallout from the collapse of major developers weighs on housing demand, prices and market confidence.
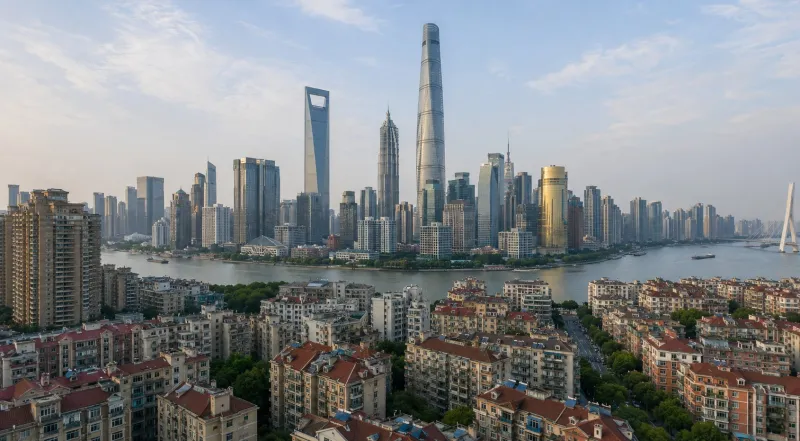
Shanghai has introduced new measures to support its residential property market as authorities intensify efforts to stabilize housing demand and restore confidence in China's struggling real estate sector.
The latest policy adjustments, which took effect on August 21, are designed to make home purchases more accessible while encouraging existing homeowners to upgrade to newer properties.
The collapse of China Evergrande has reached another major milestone after founder Hui Ka Yan was sentenced to life imprisonment by a court in Shenzhen over financial crimes linked to the property developer’s downfall.